
Calculate option call and put prices, reverse-solve implied volatility, and evaluate delta gamma theta vega risk values.
The black scholes greeks calculator helps options traders find call and put prices quickly. In addition, you can solve implied volatility (IV) and check delta, gamma, theta, vega, and rho. Enter spot price, strike price, interest rate, dividend yield, and expiry days to get instant results.
| Greek | Value | Description |
|---|---|---|
| Delta (Δ) | 0.0000 | Spot Price sensitivity |
| Gamma (Γ) | 0.0000 | Delta rate of change |
| Theta (Θ) | -₹0.00 | Daily time decay |
| Vega (V) | ₹0.00 | Price change per 1% Vol |
| Rho (ρ) | ₹0.00 | Interest rate sensitivity |
👑 Unlock Option Analytics Pro
Upgrade to the Premium Plan to unlock second-order Greeks (Vanna, Volga, Charm), IV Smile curves, IV crush crash simulator, American premium offsets, and the expected moves boundaries.
🚀 Unlock Pro Access — Add to Cart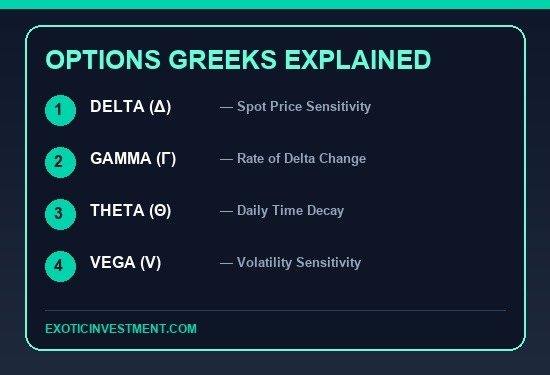
⚡ How the Black-Scholes Greeks Calculator Works
Choose Calculator Mode
First, pick option pricing mode or implied volatility solver mode. As a result, the tool updates calculation rules.
Enter Option Details
Next, type spot price, strike price, expiry date, and interest rate. Consequently, core contract settings are saved.
Set Volatility & Dividends
After that, set market volatility and expected dividend yield. Because dividend payouts lower call price, exact values help.
View Greeks & Payoff
Finally, check Call and Put values, delta gamma theta vega risk numbers, and expiry payoff charts.
🎓 Master Options Trading & Volatility Strategies!
Want to learn stock market basics and trade options with confidence? Join our easy online course today!
📋 Regulatory References & Data Sources
- Black-Scholes-Merton (1973) option pricing model
- SEBI circular SEBI/HO/MRD/DP/CIR/P/2019 — F&O margin framework
- NSE circular NSE/CMPT/39170 — SPAN margin methodology
- Securities Contracts (Regulation) Act 1956, as amended
Disclaimer: This calculator is for educational and planning purposes only. It does not constitute financial advice. Consult a SEBI-registered investment advisor for personalised guidance. Tax rules are updated as per the latest Finance Act — verify with a qualified CA before filing.
💡 Frequently Asked Questions (FAQs)
What is the Black-Scholes Model and how does it price options?
The Black-Scholes formula prices European options using spot price, strike price, expiry time, interest rate, and volatility. Specifically, our online black scholes greeks calculator solves Call and Put values instantly. Check intrinsic value on our Dividend Discount Model Calculator.
What is Delta (Δ) in options trading?
Delta shows how much an option price moves when the underlying stock moves by ₹1. For instance, a Call option with 0.50 Delta gains ₹0.50 when stock price rises by ₹1. In addition, traders use Delta as estimated ITM chance. Try portfolio setup on our Markowitz Efficient Frontier Calculator.
What is Gamma (Γ) and why is it highest at-the-money?
Gamma tracks how fast Delta changes for a ₹1 move in stock price. Consequently, high Gamma means Delta moves fast as stock price shifts. In fact, Gamma reaches peak levels for at-the-money options near expiry. Check growth rates on our PEG Ratio Calculator.
What is Theta (Θ) and how does time decay accelerate?
Theta shows how much value an option loses each day as expiry gets closer. As a result, long options lose money every day even if stock price stays flat. Specifically, Theta decay speeds up during the last 30 days before contract expiry. Check trading tax rules on our F&O Turnover Calculator.
What is Vega (V) and how does Implied Volatility affect premium?
Vega measures option price change for a 1% shift in market volatility. Therefore, higher volatility makes both Calls and Puts more expensive. Consequently, option buyers gain when volatility expands while sellers gain when volatility drops. Check brokerage fees on our Indian Stock Brokerage Calculator.
How do traders reverse-solve Implied Volatility (IV) from market price?
To solve IV, our black scholes greeks calculator uses fast root-finding steps to find exact volatility from current option prices. As a result, options traders spot mispriced trades easily. Calculate compound returns on our Lumpsum Investment Calculator.
What is Rho (ρ) in the Black-Scholes pricing formula?
Rho shows how option prices react to changes in risk-free interest rates. Specifically, higher interest rates boost Call prices and lower Put prices. In practice, Rho matters most for long-term LEAPS options. Plan money goals on our Step Up SIP Return Calculator.
Does dividend yield reduce European call option pricing?
Yes, dividend payments reduce stock price on ex-dividend dates. Consequently, higher dividend payouts reduce Call option prices and increase Put option prices. Check PE metrics on our PE Ratio Calculator.
Can investors use the Black-Scholes model for crypto derivatives?
Crypto options on Bitcoin and Ethereum trade using Black-Scholes pricing principles. Check crypto tax rules on our partner Crypto Tax Calculator India.
Why is our online black scholes greeks calculator essential for Indian index options?
Indian index options like Nifty 50 and Bank Nifty trade with high volume. Therefore, using our black scholes greeks calculator lets options buyers and sellers measure risk numbers before trading. Calculate wealth growth on our Reverse CAGR Calculator.